
Protect the Home
Your FamilyWorked So Hard For
Protect your mortgage, your income, and your family's future — with life insurance and an estate plan that work together. Local guidance for Central Valley homeowners.
Financial protection today. Clear wishes for tomorrow.
Three Pieces. One Home & Family Protection Plan.
Life Insurance
Financial support to help your family cover the mortgage and everyday expenses.
A Will
Your wishes in writing and guardian nominations for your children. A will generally does not avoid probate.
A Trust
A plan for managing and passing on assets. A properly funded trust may help your home pass outside probate.
What Protects the Mortgage if Life Suddenly Changes?
Most Central Valley homeowners insure the house itself — but not the income that actually pays the mortgage, the bills, and everything else inside it. Term life insurance can help create a financial safety net for the people who depend on you most.
What the Right Coverage Can Help You Protect
Six everyday things term life insurance with living benefits is designed to help protect.
Protect the Mortgage
Term life insurance can help your family keep paying the mortgage and stay in the home you worked so hard to buy, even if your income is suddenly gone.
Protect the Family Income
Coverage can help replace the income that pays for groceries, utilities, childcare, gas, car payments, and the everyday bills that keep a household running.
Protect Your Children's Future
From school and childcare today to college and bigger life moments later, the right policy can help keep your kids' future on track if life changes unexpectedly.
Protect Loved Ones From Final Expenses
Coverage can help cover funeral costs, medical bills, and the unexpected expenses that often fall on a spouse or parent during an already painful time.
Protect Your Business or Side Income
If you're self-employed or own a small business that helps support the household, life insurance can help protect that income stream for your family.
Protect You While You're Still Living
Many term life policies include living benefits that may let you access funds early if diagnosed with a qualifying serious illness — money that can help with the mortgage, bills, and recovery.
Who Should Think About Mortgage & Family Protection?
If a mortgage, a child, or a partner depends on your income, coverage is worth a conversation.
- New homeowners
- First-time buyers
- Young & growing families
- Parents with young kids
- Married couples with a mortgage
- Single-income households
- Self-employed homeowners
- Anyone protecting a mortgage or income
Real-Life Homeowner Situations We Help With
The First-Time Buyer
A young couple just closed on their first home. They want to make sure the mortgage wouldn't become a crushing burden on the other person if one income suddenly disappeared.
The Growing Family
Parents with young kids want coverage that helps protect the mortgage, daycare, groceries, and their children's long-term stability — no matter what life throws at them.
The Single-Income Household
One spouse works while the other is home with the kids. They want a safety net so the family can stay in the home and keep their lifestyle if that income is ever interrupted.
You Worked Hard for This Home. Plan Who Receives It.
Protecting the home means thinking about both the money your family may need and the wishes you want honored. Life insurance, a will, and a properly funded trust can play different, complementary roles.
Your home may be your largest asset — and your family's most familiar place. A will records your wishes and guardian nominations; a properly funded trust may help transfer the home outside probate. An estate-planning attorney can guide you based on your home's ownership, family situation, and California law.
Life insurance can provide the funds. Estate planning helps document the wishes. Together, they help your family prepare.
Help the Home Pass Outside Probate
Probate is the court process for administering certain estate assets. A will generally does not avoid it. A properly funded trust may help your home pass to your chosen beneficiaries outside probate; title, ownership, and your circumstances matter.
Nominate a Guardian for Your Children
A will lets you nominate the person you want to care for your minor children. A court makes the final appointment based on their best interests, but documenting your wishes gives your family important guidance.
Plan How Your Children Receive Support
Naming a minor directly as a beneficiary can complicate access to insurance proceeds. With attorney guidance and coordinated beneficiary designations, a trust can set terms for using funds toward housing, childcare, education, and later distributions.
Protect a Spouse, Partner, or Blended Family
In second marriages, blended families, or unmarried couples, the house can legally pass to someone other than the partner still living in it. An attorney-designed plan can clarify your wishes and help coordinate ownership and inheritance, subject to debts, legal rights, and your circumstances.
Plan Ahead to Reduce Pressure to Sell
Life insurance can provide funds for a mortgage and other expenses, while estate planning clarifies how the home is managed and transferred. Together they may reduce financial pressure to sell, but a trust does not eliminate debts or guarantee the home will stay in the family.
Keep Legal Costs and Public Records Down
Probate proceedings are generally public. A properly funded trust may provide greater privacy and reduce probate-related delays and costs for assets it holds, though trust administration still has costs and legal requirements.
What a Complete Plan Usually Includes
Start with what you have. An estate-planning attorney can help determine which documents you need and coordinate them with your home's ownership and insurance beneficiaries.
- A last will & testamentRecords your wishes and nominates a guardian for minor children, subject to court approval.
- A revocable living trustMay help assets it holds pass outside probate; insurance beneficiaries must be coordinated with your attorney.
- Current beneficiary designationsOn life insurance and retirement accounts — these usually override a will.
- A deed coordinated with the trustThe home's title actually has to be moved into the trust for it to work.
- Durable power of attorney & healthcare directiveSo someone you trust can act and make decisions if you can't.
- One written summaryMortgage, accounts, policies, and where the documents are kept.
Put the Protection and the Plan in the Same Conversation
In your free review we'll look at the mortgage, your income, and who depends on you — then help you see how a policy, your beneficiary designations, and a will or trust fit together. If you don't have estate documents yet, we can connect you with licensed estate planning professionals.
Central Valley Experior is not a law firm, attorney, or tax advisor and does not prepare wills, trusts, deeds, or other legal documents. Estate planning laws vary by state and personal situation. This content is for educational purposes only and is not legal or tax advice — talk with a licensed estate planning attorney about your own plan.
What Happens to the Mortgage if a Serious Illness Stops Your Income?
Most people think life insurance only helps after death. But many modern term life policies also include living benefits that may provide financial support if you experience a qualifying serious illness while still living — exactly when a homeowner needs it most.
A cancer diagnosis, heart attack, or stroke can affect far more than your health. It can interrupt your income while the mortgage, utilities, groceries, childcare, and car payments all keep coming. Some term life insurance policies may allow access to benefits early if diagnosed with qualifying conditions — money that can help keep your family in the home.
What If You Were Diagnosed With Cancer?
A cancer diagnosis often means missed work, treatment costs, travel, and time away from the family — while the mortgage, utilities, and groceries keep arriving. Living benefits on a qualifying term life policy may allow access to funds early that can help cover the home payment, bills, and recovery time.
What If You Suffered a Heart Attack?
Recovery from a heart attack can require weeks or months away from work and major lifestyle changes. For a homeowner, that gap in income can quickly put the mortgage and household bills at risk. Living benefits may help bridge that period so your family can stay in the home.
What If a Stroke Changed Your Ability to Work?
A stroke can change income, mobility, and long-term responsibilities almost overnight. Living benefits may help families cover the mortgage, rehab, caregiving costs, and the everyday expenses that don't pause just because life suddenly did.
Protecting the Income That Protects Everything Else
Your income is what pays the mortgage, fills the fridge, gets the kids to school, and keeps the lights on. Term life insurance with living benefits is designed to help protect that income — and the home and family that depend on it — if life suddenly changes.
Living benefits riders may vary by carrier, policy, state, and eligibility requirements. Benefits may be subject to limitations, exclusions, waiting periods, and qualifying conditions. This content is for educational purposes only and is not a guarantee of coverage or benefits.
Protect Your Family & Your Mortgage Before Life Changes Unexpectedly
See How Affordable Term Life Insurance Can Be for a Homeowner
Use the sliders below to see a general sample range for the kind of term life insurance many homeowners choose to help protect the mortgage, their income, and their family. Actual pricing depends on age, health, tobacco use, carrier, underwriting, state, and coverage amount.
Sample Term Life Estimate
Estimated sample range
$41–$60/ month
This is only a general educational estimate. Actual rates vary by carrier, age, health, state, tobacco use, underwriting, policy type, riders, and coverage amount. A licensed agent can provide a personalized quote.
What Are You Most Focused on Protecting?
Pick what matters most — your mortgage, your income, your kids, or your estate plan — and we'll tailor your free review around it.
Protecting Your Home & Family Starts With One Conversation
Get a personalized protection review built around your mortgage, your income, and your family. No pressure — just education, options, and honest guidance from a local Central Valley agent.
Request Your Free Home & Family Protection Review
A licensed local agent will follow up about your home, mortgage, and family protection needs, including how insurance fits with your estate plan — no pressure.
Life insurance coverage, benefits, riders, and eligibility vary by carrier, product, state, age, health, underwriting, and individual situation. Living benefits may be subject to qualifications, limitations, and availability. This page is for educational purposes only and does not guarantee approval or coverage.
Frequently Asked Questions
Answers about mortgage protection, living benefits, and how wills and trusts fit into a homeowner’s plan.
The Person Behind Your Protection Plan
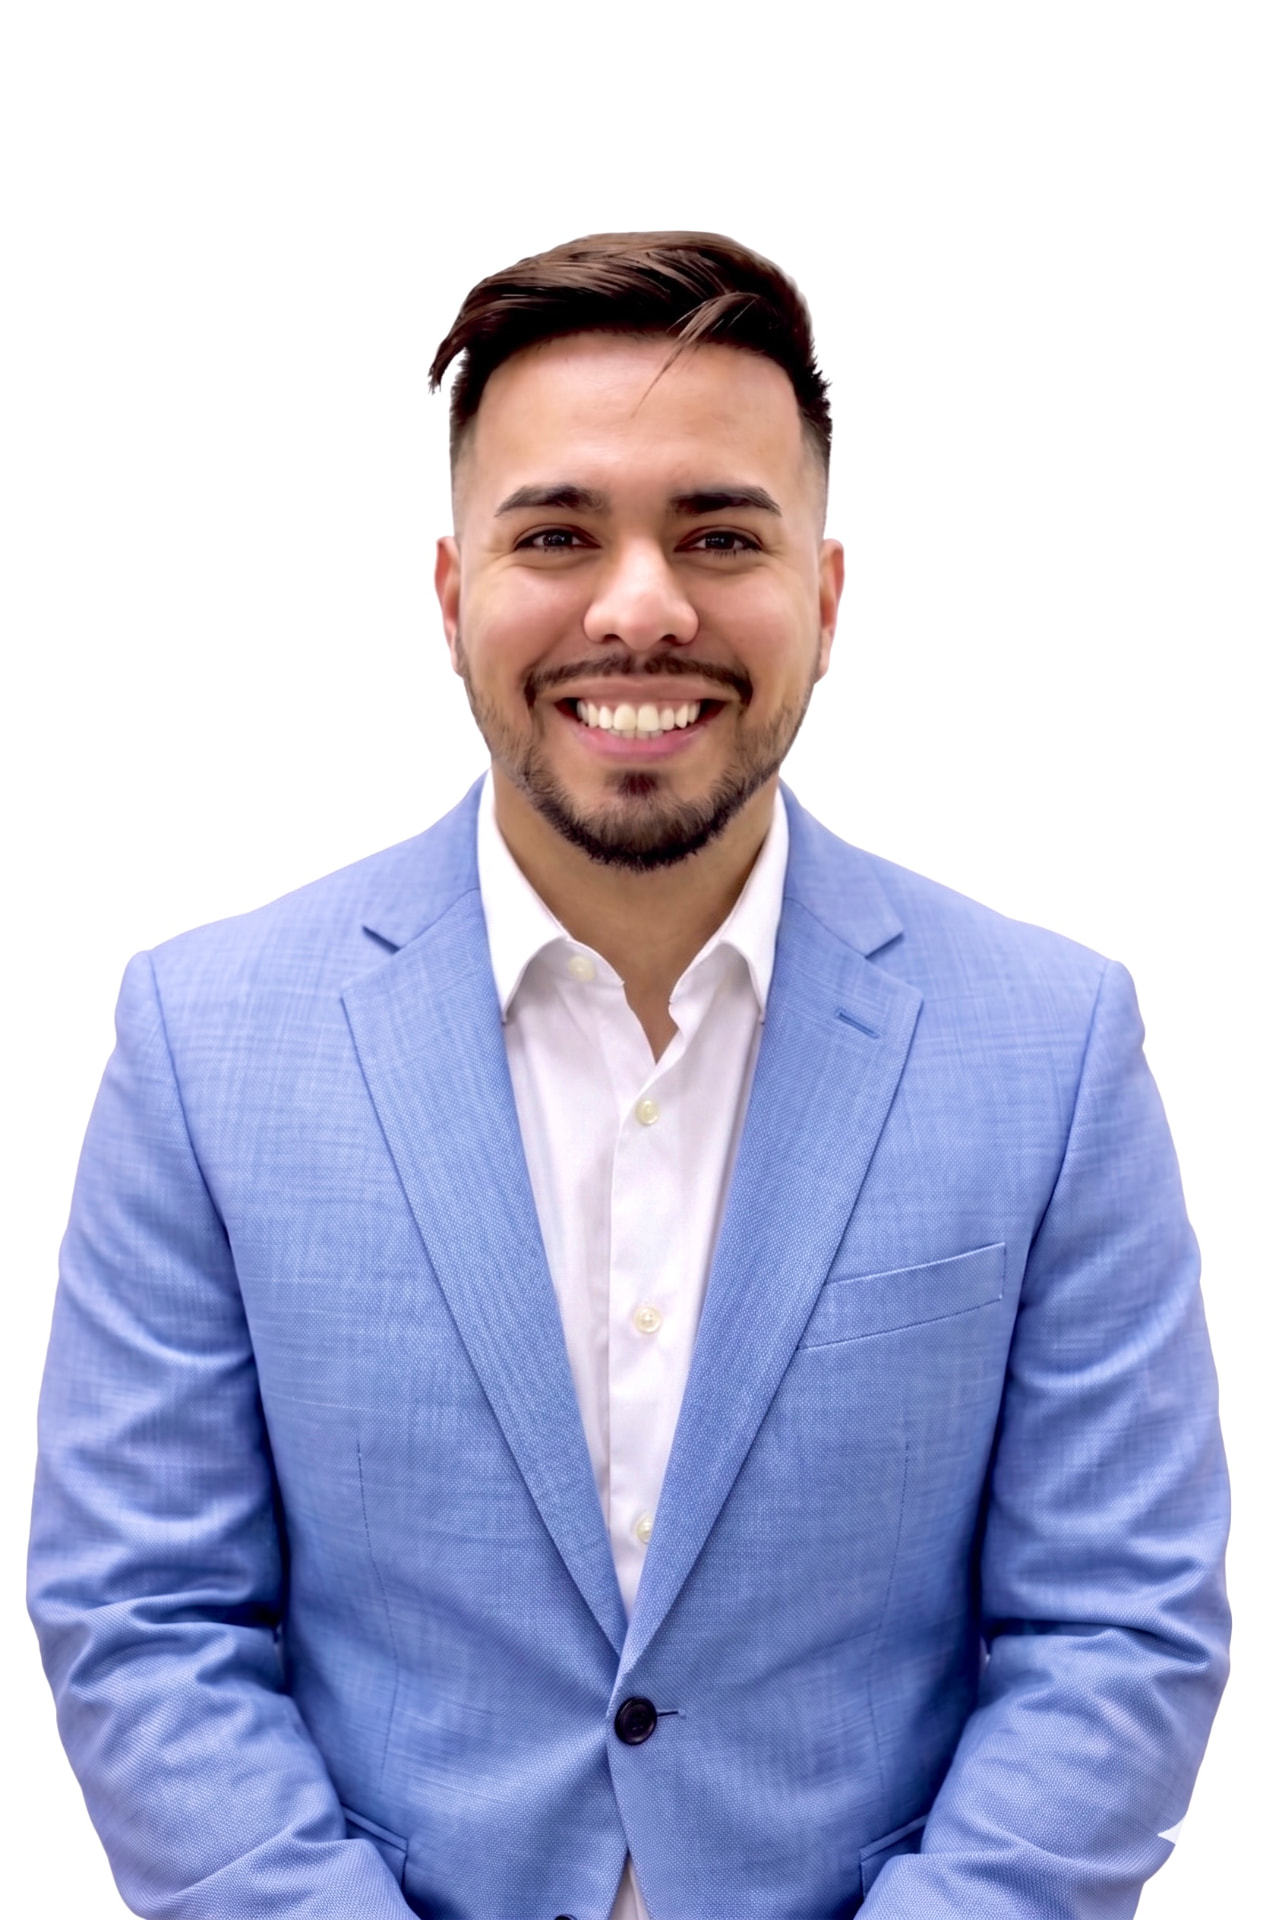
Jorge Ceballos
Licensed Insurance Agent — Central Valley Experior
Jorge helps Central Valley families — especially new homeowners and growing families — put a real protection plan in place. That means looking at the whole picture: life insurance to protect the mortgage and your income, living benefits for the unexpected, and making sure your will or trust works together with your coverage so the home ends up in the right hands.
No pressure, no jargon — just a straightforward conversation about what your family actually needs, in English or Spanish.
- 559.259.5500— call or text
- jorgec.efg@gmail.com
- Serving Fresno, Visalia, Bakersfield & the Central Valley